

Quick Answer. Reactive benefits pay when something goes wrong, and preventive benefits help employees stay well. Most employers need both. Spending accounts can support prevention by covering screenings, vaccines, fitness and mental health support, while group insurance and public plans handle major treatment.
Most benefits plans were built to respond to illness: they reimburse a prescription, a dental procedure or a treatment after the need has appeared. Prevention works earlier, by helping people stay healthy, catch problems sooner and manage conditions before they become expensive. This guide offers a simple four-level framework that shows where preventive and reactive benefits sit, how health and wellness spending accounts can support the early levels, and what Canadian data says about why it matters.
Key Takeaways
- The Public Health Agency of Canada reports that 44% of adults aged 20 and older have at least one of 10 common chronic conditions.
- Prevention and management of chronic disease are both needed, according to the agency.
- CRA lists vaccines and laboratory tests as eligible medical expenses, while gym and fitness club fees are not eligible, which maps prevention across both account types.
- A four-level framework helps decide which benefit fits which stage.
- Spending accounts are flexible, but they do not replace group insurance or public coverage.
What Counts as Preventive and What Counts as Reactive?
Reactive benefits respond to a need that has already appeared, such as treatment, medication or a procedure. Preventive benefits aim to reduce the chance or severity of a need, such as screenings, vaccinations, fitness and early mental health support. Most real plans are a mix, and many services sit in between.
Why Does Prevention Matter?
The Public Health Agency of Canada’s infographic on the prevalence of chronic diseases among Canadian adults reports that 44% of adults aged 20 and older have at least one of 10 common chronic conditions, including hypertension at 25%, osteoarthritis at 14% and mood or anxiety disorders at 13%. The data are from 2015 to 2016, but they show how common these conditions are in working-age and older adults. A separate agency summary, How Healthy Are Canadians?, states that healthy living, prevention and adequate management of chronic diseases are all necessary for Canadians to live long, healthy lives.
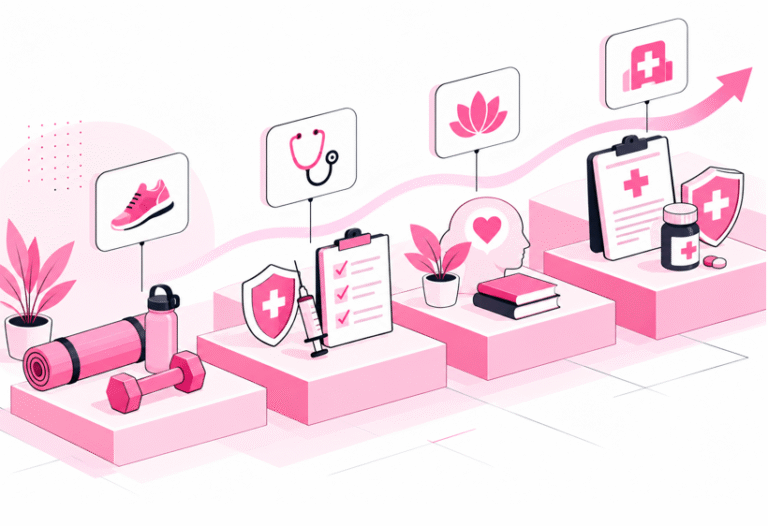
The Four-Level Framework
| Level | What it covers | Examples | Typical account fit |
| 1. Healthy habits | Staying active and well | Gym memberships, fitness classes, yoga | Wellness Spending Account |
| 2. Screening and vaccines | Catching problems early | Vaccines, laboratory tests, eye and dental exams | Health Spending Account, subject to plan rules |
| 3. Early support | Help before a problem grows | Paramedical care, some mental health services | Health or Wellness Spending Account, depending on the service |
| 4. Managing conditions | Ongoing care | Prescriptions, devices, treatment | Group insurance or Health Spending Account |
Where Do Spending Accounts Fit?
The Health Spending Account for Care
The CRA’s page on eligible medical expenses lists vaccines, laboratory procedures and services, dental services and vision devices as eligible medical expenses, some with a prescription. Because a Health Spending Account follows the medical expense rules, those prevention-oriented items fit there.
The Wellness Spending Account for Habits
The same CRA list shows athletic or fitness club fees and vitamins and supplements as not eligible medical expenses. That is where a Wellness Spending Account helps: it can cover gym memberships, classes and other habit-building spending that a medical-only account cannot. The trade-off is that benefits outside a qualifying private health services plan are generally taxable, so check each category with a payroll professional.
A Simple Way to Decide
Ask three questions. First, what do employees already pay for out of pocket in each of the four levels? Second, which of those would help most if it were easier to afford? Third, which account type can legitimately cover each item? The answers give you a short list of categories and allowances to start with, and you can adjust after a few months of claims data.
How Does One Platform Frame Prevention?
One published example is the preventive healthcare piece in GoKlaim‘s use cases, which describes how routine screenings, vaccinations, fitness programs and mental health services can help reduce chronic disease risks and support well-being. Employers choose the categories and allowances through its Health and Wellness Spending Accounts, and GoKlaim’s accounts can complement group insurance or replace it , so preventive spending can sit alongside whatever core coverage a company has.
Conclusion
Prevention is not a replacement for treatment, and treatment is not a substitute for prevention. A healthy benefits design puts both in the picture. Start with the four levels, check which are covered today and look for the gaps that employees feel most. Use a Health Spending Account for what the medical rules allow and a Wellness Spending Account for the habits that keep people well. Then track what people use, ask them what helps, and change the mix as you learn. Small, steady support for staying healthy is easier to sustain than a crisis response, and it is usually welcomed by the people it is meant to help.
Frequently Asked Questions
Can a spending account cover preventive care?
Yes, within the plan’s rules. A Health Spending Account can cover eligible medical items such as vaccines and lab tests, and a Wellness Spending Account can cover fitness and other habits.
Is a gym membership an eligible medical expense?
Not according to the CRA, which lists athletic or fitness club fees as not eligible. A Wellness Spending Account can cover it as a wellness category.
Do spending accounts replace group insurance?
They can for some small employers, but they work differently from group insurance. Many employers use both.
How do I know what my team needs?
Start with claims and out-of-pocket data, then ask employees which costs matter most.
Are wellness spending account benefits taxable?
They can be. Benefits that do not qualify as eligible medical expenses under a private health services plan are generally treated as taxable benefits. Employers should confirm the tax treatment of each category with a payroll or tax professional.
How should employers choose between a Health Spending Account and a Wellness Spending Account?
Start by separating medical expenses from wellness expenses. Use a Health Spending Account for eligible medical expenses under CRA rules, and use a Wellness Spending Account for categories such as fitness and other wellness activities that do not qualify as medical expenses.